Soft play insurance
Insurance for a soft play business should identify fixed structures, inflatables, climbing equipment, capacity and maintenance. Insurance for soft play should not be assumed to extend to every attraction at the venue.
Indoor playground insurance should describe the equipment, age groups and supervision at the facility. Liability insurance for an indoor playground needs review of the actual activities, not just the business name.

 A.M. Fredericks UnderwritingABEX o/b Affiliated Broker Exchange
 Allianz Global RisksAmbri AssuranceApril Canada Inc.April MarineArthur J. Gallagher & Co
 AVRO Insurance ManagersBeazley Canada LimitedBerkley Insurance CompanyBlueCross BlueShield
 Burns & Wilcox CanadaCAA InsuranceCAN - Continental Insurance
 Cansure Underwriting LtdCaradoc Townsend MutualChes Special Risk Inc.Chubb InsuranceChutter Underwriting Services
 Core Underwriting ServicesDefinityDesjardins Financial Security Investments Inc.
 Dominion of Canada/Travelers/Travelers EssentialEagle Underwriting Group Inc.Echelon
 Excess Underwriting Corp.Facility Association
 Forward InsuranceGlobal Aerospace Underwriting
 Great-West LifeGroupAssureGroupOne Insurance
 HDI Global Specialty SE
 IA Excellence Life Insurance
 INGLE International
 Intact Public Entities
 La CapitaleLiberty International CanadaLynx Insurance UnderwritersMarkel
 NorthbridgeOld Republic
 Optiom
 PAL Insurance Brokers Canada
 Premier Canada AssurancePremier MarinePremium Marine
 Revolution Advanced Underwriting
 SignalSignature Risks
 South Western GroupSovereign GeneralSpecial Risk InsuranceSports & Fitness InsuranceSSQ AssuranceStarr Technical RisksStrategic UnderwritingSummit Underwriting Group Inc.The Boiler Inspection and Indemnity Company (BI&I)
 The Totten Insurance GroupTrans Canada
 TravelersTrinity Underwriting
 Unique Risks
 Victor Insurance
From Insurance Genie
Explore recent policy purchases shared through our participating insurance professionals.
Recent policies will appear here when the Insurance Genie CRM feed is connected.
Insurance Genie is an insurance request platform, not an insurer or insurance brokerage. Requests may be connected with participating licensed partners. Availability depends on your location, needs and partner eligibility. A request is not a quote or confirmation of coverage.
Use these topics to frame a discussion with the licensed professional handling your request. They are questions to review, not a promise that every item is included in a policy.
Describe the full activity, including work away from the main premises and any secondary services. An incomplete description can make two proposals look comparable when they are based on different information.
Ask for the named insured, business description, covered locations, policy limits, deductibles and key exclusions. Check how defence costs, property valuation and any required endorsements are treated. A policy title alone does not tell you what an individual claim would receive.
If a landlord, lender, marketplace or customer has supplied insurance conditions, provide the actual document. Ask the licensed professional to identify requirements the proposed policy does and does not satisfy. A certificate is evidence of stated coverage; it should not be treated as a rewrite of the policy.
The price depends on the business activity, scale, location, claims history and selected protections. Request a review using your own facts instead of treating a generic industry range as a quote.
Insurance Genie connects requests with participating licensed partners. Products, territories and eligibility vary. Confirm who is handling your request and when any offered coverage would take effect.
Your questions, answered
Insurance for indoor playground operations should describe the play structures, age groups and supervision.
Insurance for a soft play business should identify fixed structures, inflatables, climbing equipment, capacity and maintenance. Insurance for soft play should not be assumed to extend to every attraction at the venue.
Describe admission, parties, supervision and safeguarding procedures. Ask how the policy treats participant injury allegations, special activities and independent operators.
Explain the cafe, food preparation, party service and play area together. Food service and play activities create different questions and should both appear in the provider’s review.
Indoor playground insurance cost needs a site-specific assessment of activities, equipment, attendance, supervision, claims and requested cover. A generic average cost of commercial insurance does not describe those details.
No. Ask how safety procedures, documented inspections and waivers support the risk review, while confirming the actual coverage, exclusions and reporting obligations separately.
Provide an equipment and activity list, age groups, capacity, revenue, inspections, staff procedures, party arrangements and any lease requirements. Explain temporary or seasonal attractions before relying on existing cover.
The activities, equipment, attendance, supervision, claims history and selected coverage all matter. A site-specific request is more useful than a generic average premium.
Prepare the activity description, current insurance, recent claims details and any contract requirements. Include the business-specific information listed on this page so the licensed partner can ask relevant follow-up questions.
No. A request is not a binder, policy or confirmation of coverage. The organization arranging insurance must confirm acceptance, terms and the effective date.
Indoor playground insurance discussions should start with what visitors can actually do. List soft-play structures, climbing activities, inflatables, parties, food service and any supervised drop-off sessions separately. Explain the ages served, capacity, operating hours and who supervises each area. Ask the licensed professional to identify any activity restrictions in the proposed wording, rather than relying on the broad description of a children's play centre.
Compare customer liability questions with damage to equipment and tenant improvements. Bring inspection and maintenance records, incident procedures and the lease. Ask how temporary closures would be assessed and what events must trigger any proposed business interruption cover.
To explore indoor playground insurance savings, keep your activity list and equipment values current. Explain documented inspections and staff training without assuming they create an automatic discount. Ask whether a change in activities, hours or capacity affects the proposal. Compare the full conditions of each option, including deductibles that the business can afford, before focusing on the premium difference.
Hypothetical example: a soft-play centre plans to introduce an inflatable attraction for birthday parties. Before taking bookings, its owner should ask the insurance professional to review the new activity, supervision arrangements and supplier contract. Existing wording may need a separate discussion. This scenario is a planning checklist, not confirmation that an attraction or incident would be covered.
This page is general information. Ask the licensed professional handling your request to explain the proposed wording, limits, deductibles and exclusions. Coverage must be confirmed by the organization arranging it.
Background reading: Consumer insurance coverage guidance. Content updated September 9, 2026; coverage and availability remain subject to confirmation.
Contact us to discuss provider availability and the details needed for a useful conversation.
Explore my optionsBefore you compare
Indoor playground insurance should account for equipment, age groups, supervision and special events. Insurance for a soft play business and insurance for a play cafe should explain the play activities and any food service together.
List play structures, inflatables, climbing or trampoline activities, supervision, capacity and maintenance procedures. Describe parties, drop-off programmes and any activities run by outside operators.
The insurer reviews the activities, scale, claims history, controls and requested terms. Compare proposals with the same equipment and operations description, and ask about participant-related exclusions, deductibles and limits.
A practical comparison guide
Explain age groups, maximum occupancy, staff supervision and how different activities are separated. Keep equipment inspection, cleaning and repair logs. Record how incidents are reported and escalated. Include party hosts, contractors and any drop-off childcare arrangements so the provider can distinguish a play facility from other services.
Ask about participant injuries, premises liability, equipment and business interruption. Discuss allegations involving supervision, abuse or misconduct explicitly; do not assume general liability addresses every allegation. Waivers, signs and safety rules support operations but do not replace policy wording or legal review.
Use current documents. If a detail is uncertain, identify it for the provider instead of guessing.
No. A waiver does not stop someone from alleging negligence, and its effect depends on the circumstances and applicable law. Have a qualified adviser review the document and ask the insurance provider how defence costs and participant claims are addressed.
Terms depend on the facts supplied, the requested protection and the provider’s assessment. Compare the full annual cost, limits, deductibles and conditions. An illustration or general guide is not a personal quote or confirmation of coverage.
Insurance Genie helps you prepare an insurance enquiry. A participating licensed professional must confirm availability and the terms of any proposal. For legal or contractual obligations, obtain advice from the appropriate qualified adviser.
Discuss my requirements →Further reading: Insurance Bureau of Canada guidance. Check the current document and your own policy or bond wording. This page is general information, not an issued policy or bond.
Be prepared
Hypothetical situations to help you prepare questions—not actual client claims or promises of coverage.
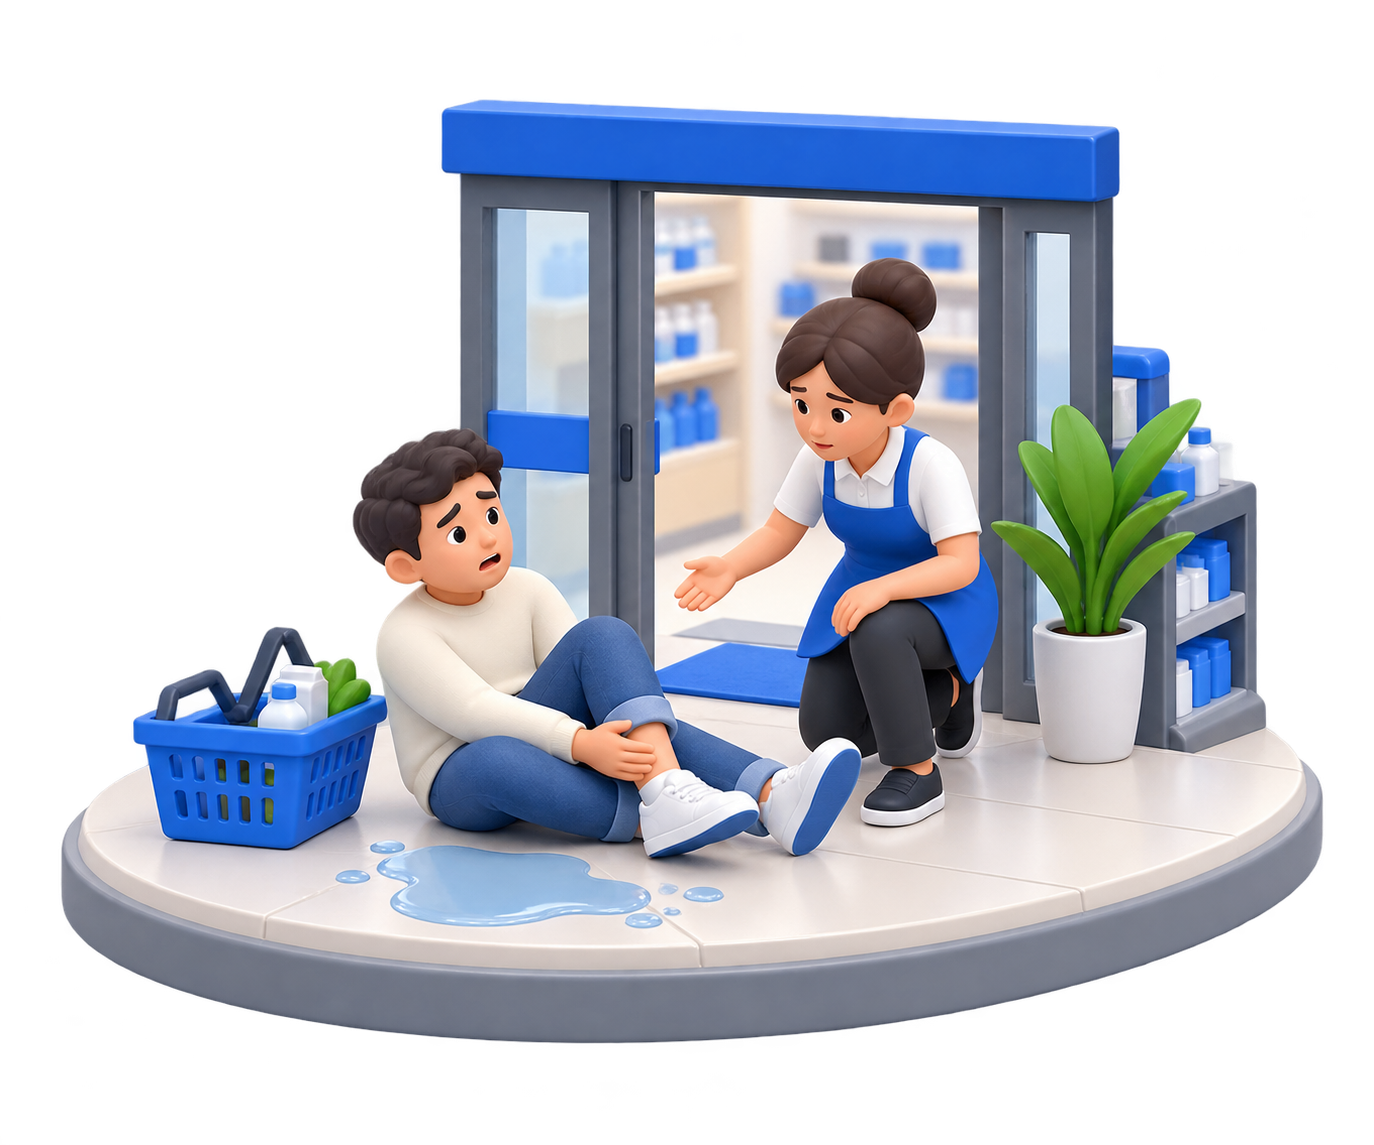
Scenario: Someone alleges an injury arose from the business operations.
What happens next: Preserve incident records and notify the insurer. Declared activities, liability wording and the facts determine whether a policy responds.
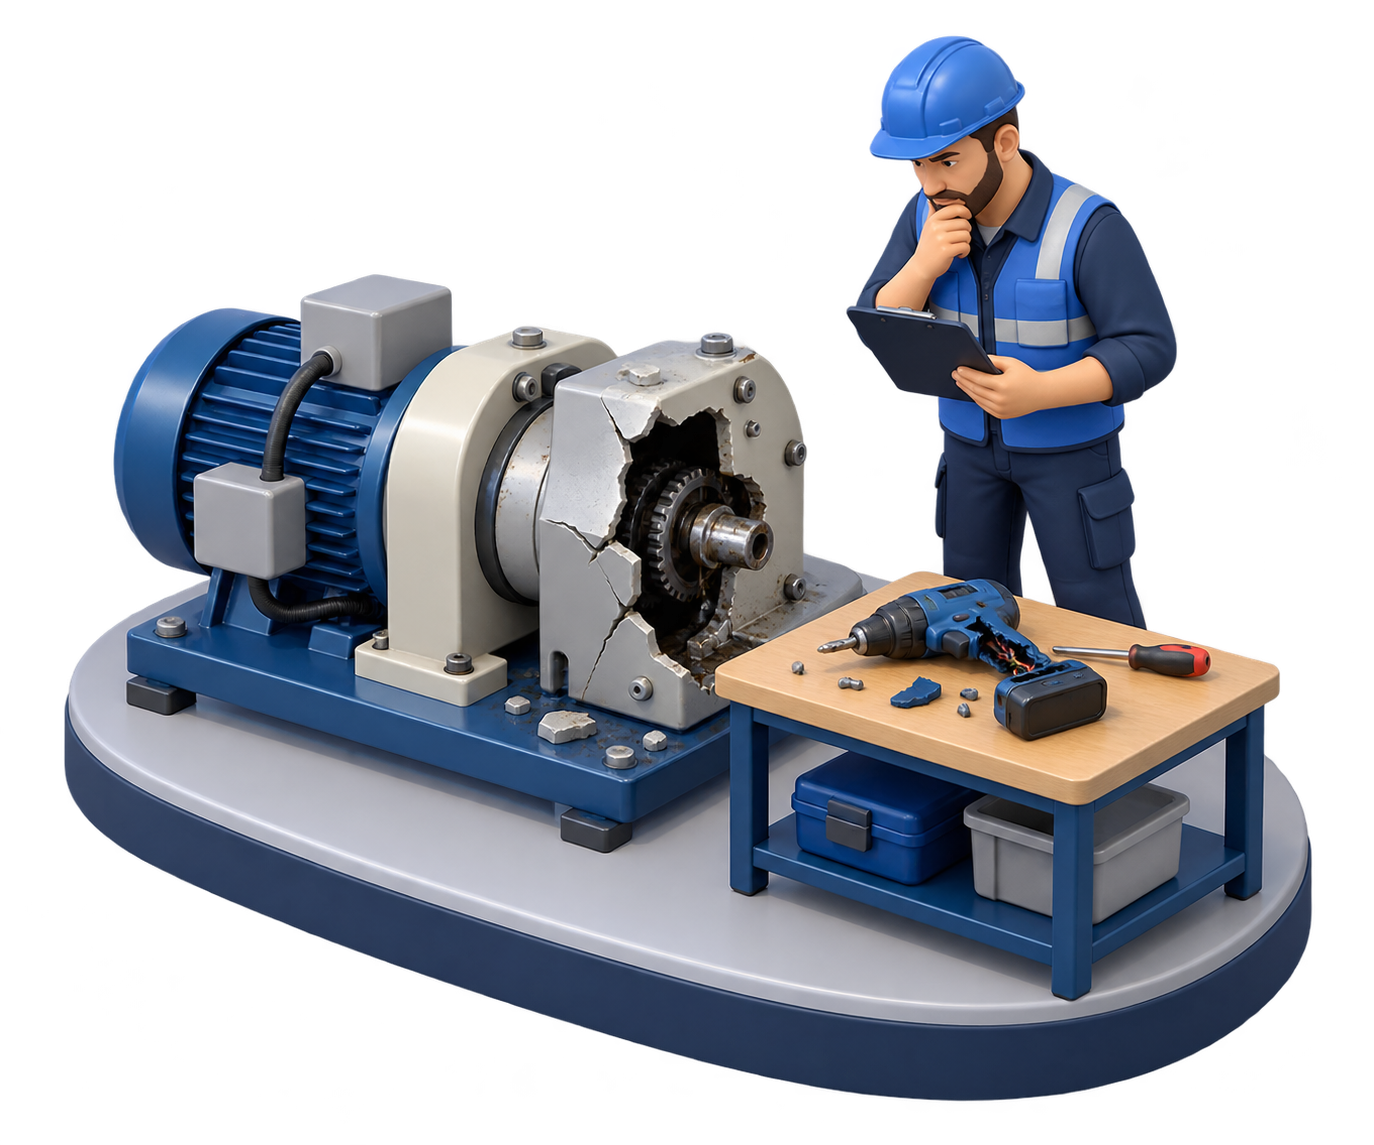
Scenario: Equipment used by the business is damaged or stolen.
What happens next: Document ownership, location and cause. Ask the insurer to review the insured property, exclusions, valuation and deductible.
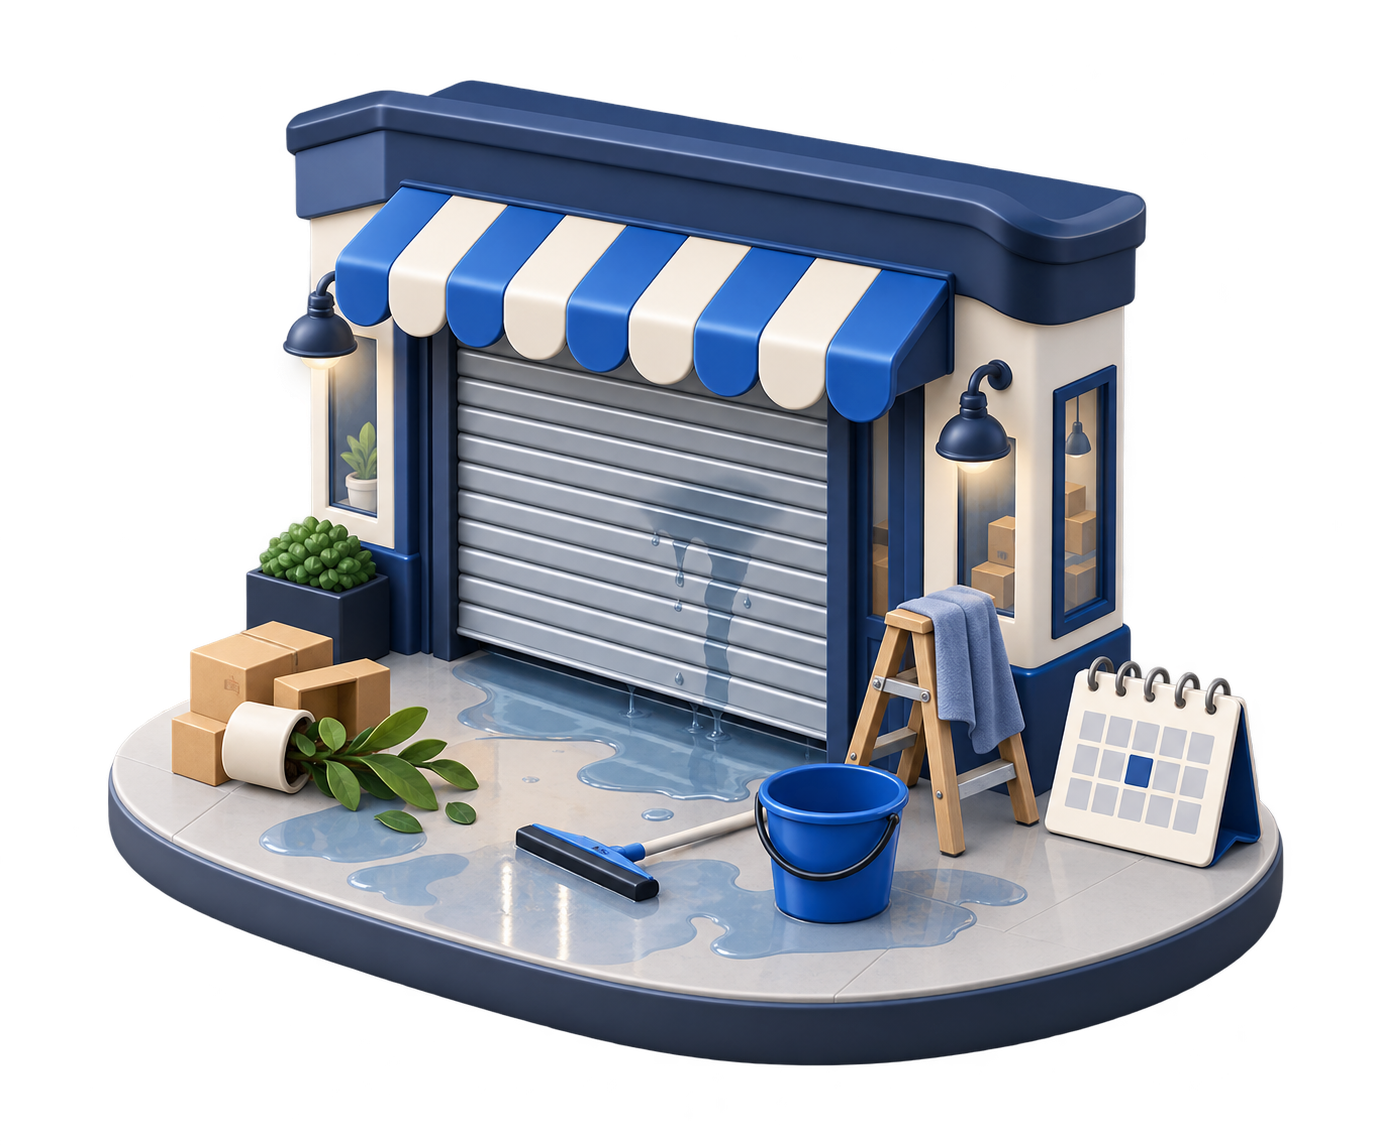
Scenario: Damage prevents the business from operating normally.
What happens next: Keep revenue and expense records. Business interruption depends on the insured trigger, selected coverage and applicable terms.
Actual outcomes depend on the facts and applicable wording. Read claims guidance · Ask about the next step
Hi, I’m Genie. I can explain how this website works, help you find a page, or point you to a person. I can’t answer coverage questions or give insurance advice.