Home Insurance

Tenant Insurance

Tenant insurance is for renters who need to review their belongings and personal liability. Your landlord's building policy does not stand in for a policy covering your own interests.

  • House, condo & tenant
  • Coverage and cost together
  • No obligation to buy
Let’s find your next stepNo obligation to buy

Continue to call or email about your property. This step does not submit an application.

20%
What could a lower premium mean for you?Illustrative example: $2,400 → $1,920 per year is $480 less. Not an available offer. Try your own numbers →
The original Insurance Genie character
Your life. Your coverage.Compare the details that matter to you
A little guidance goes a long way.Explore your next step with confidence
Live examples
CRM examples will appear here once the feed is connected.

From Insurance Genie

Recent home insurance purchases

Explore recent policy purchases shared through our participating insurance professionals.

Recent policies will appear here when the Insurance Genie CRM feed is connected.

A practical comparison guide

Build a realistic belongings inventory

Walk through each room and estimate the cost of replacing clothing, furniture, electronics and other possessions. Keep photos and receipts somewhere accessible if you cannot enter the home. Ask about bicycles, jewellery and other items with special limits. Explain roommates, subletting and business use before choosing a policy.

Tenant Insurance planning illustration

Questions to bring to the discussion

Compare proposals using the same occupancy, property information and requested protections. Record each deductible, any special limit and the settlement basis. Ask for an explanation of exclusions and duties that apply while the property is unattended. Keep a copy of the wording and the answers you relied on, rather than comparing only the monthly payment.

Prepare these details

  • Rental address and lease
  • Occupants and roommates
  • Belongings and valuables
  • Required liability limit

Use current documents. If a detail is uncertain, identify it for the provider instead of guessing.

Your questions, answered

Can roommates share one tenant policy?

Do not assume every occupant is insured. Give the provider the household arrangement and ask who qualifies as an insured person. Separate agreements or policies may be needed depending on the insurer and relationship.

What affects the terms I can obtain?

Terms depend on the facts supplied, the requested protection and the provider’s assessment. Compare the full annual cost, limits, deductibles and conditions. An illustration or general guide is not a personal quote or confirmation of coverage.

Bring the right details. Get a clearer answer.

Insurance Genie helps you prepare an insurance enquiry. A participating licensed professional must confirm availability and the terms of any proposal. For legal or contractual obligations, obtain advice from the appropriate qualified adviser.

Discuss my requirements →

Related guides

Further reading: Insurance Bureau of Canada guidance. Check the current document and your own policy or bond wording. This page is general information, not an issued policy or bond.

Be prepared

Claims scenarios: what happens next?

Hypothetical situations to help you prepare questions—not actual client claims or promises of coverage.

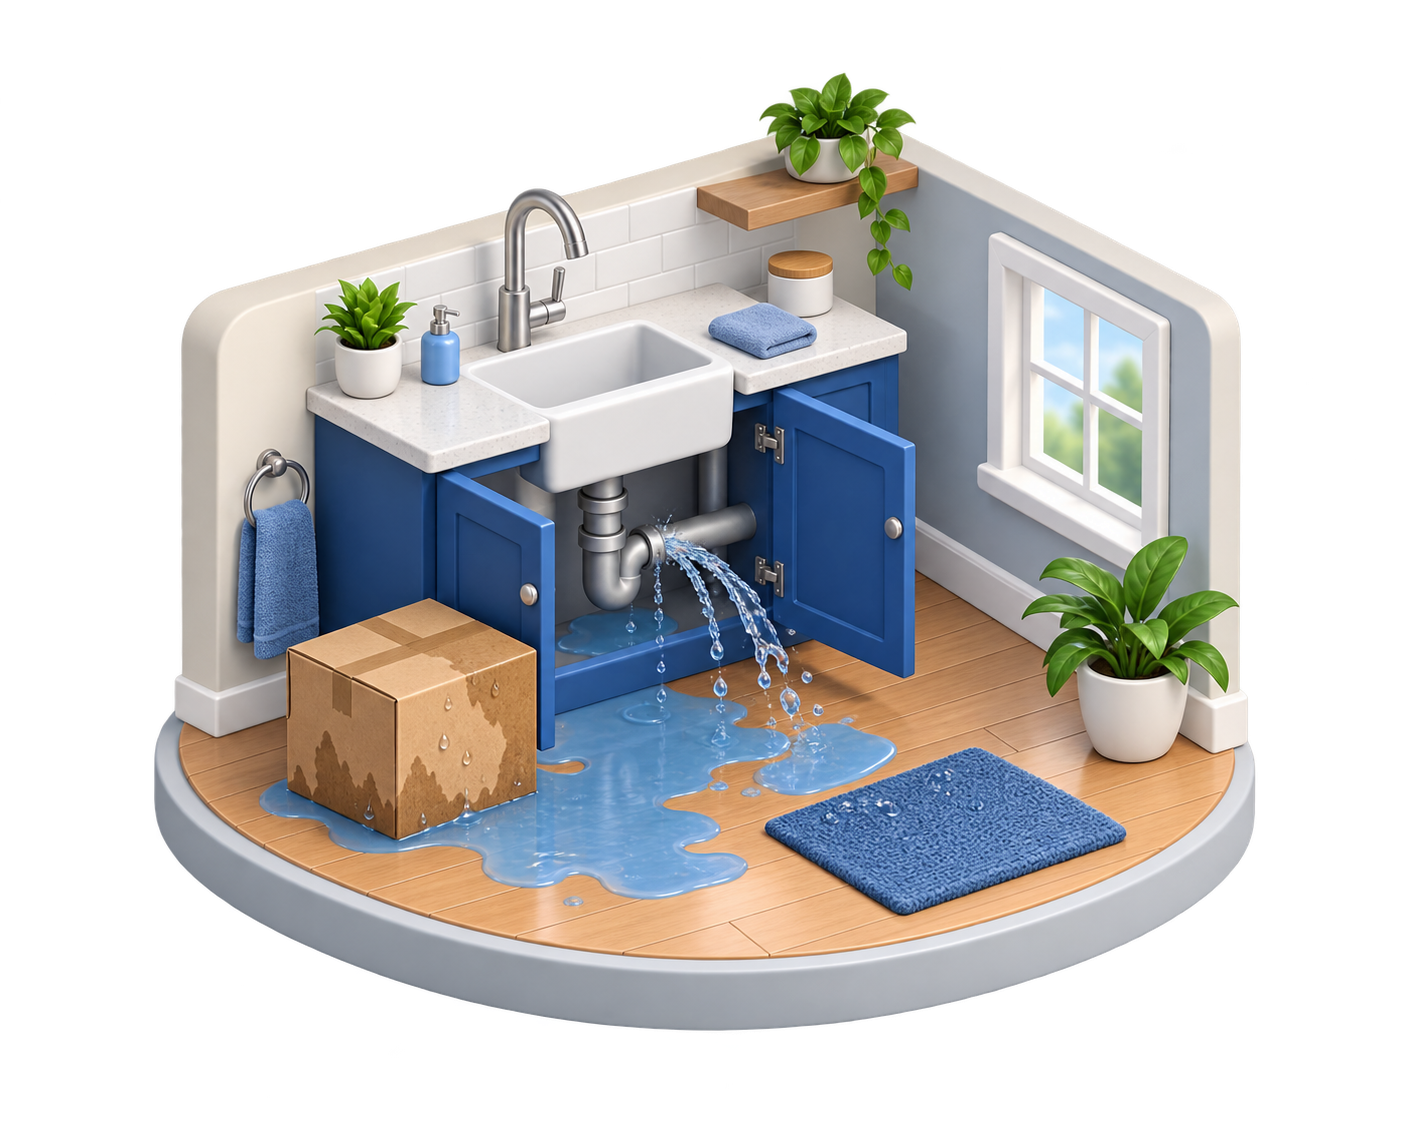
A burst pipe leaking onto a home floor

Sudden water damage

Scenario: A pipe breaks and damages flooring and belongings.

What happens next: Document the source and damage. The insurer will review the cause, policy wording, limits and deductible; different water events have different treatment.
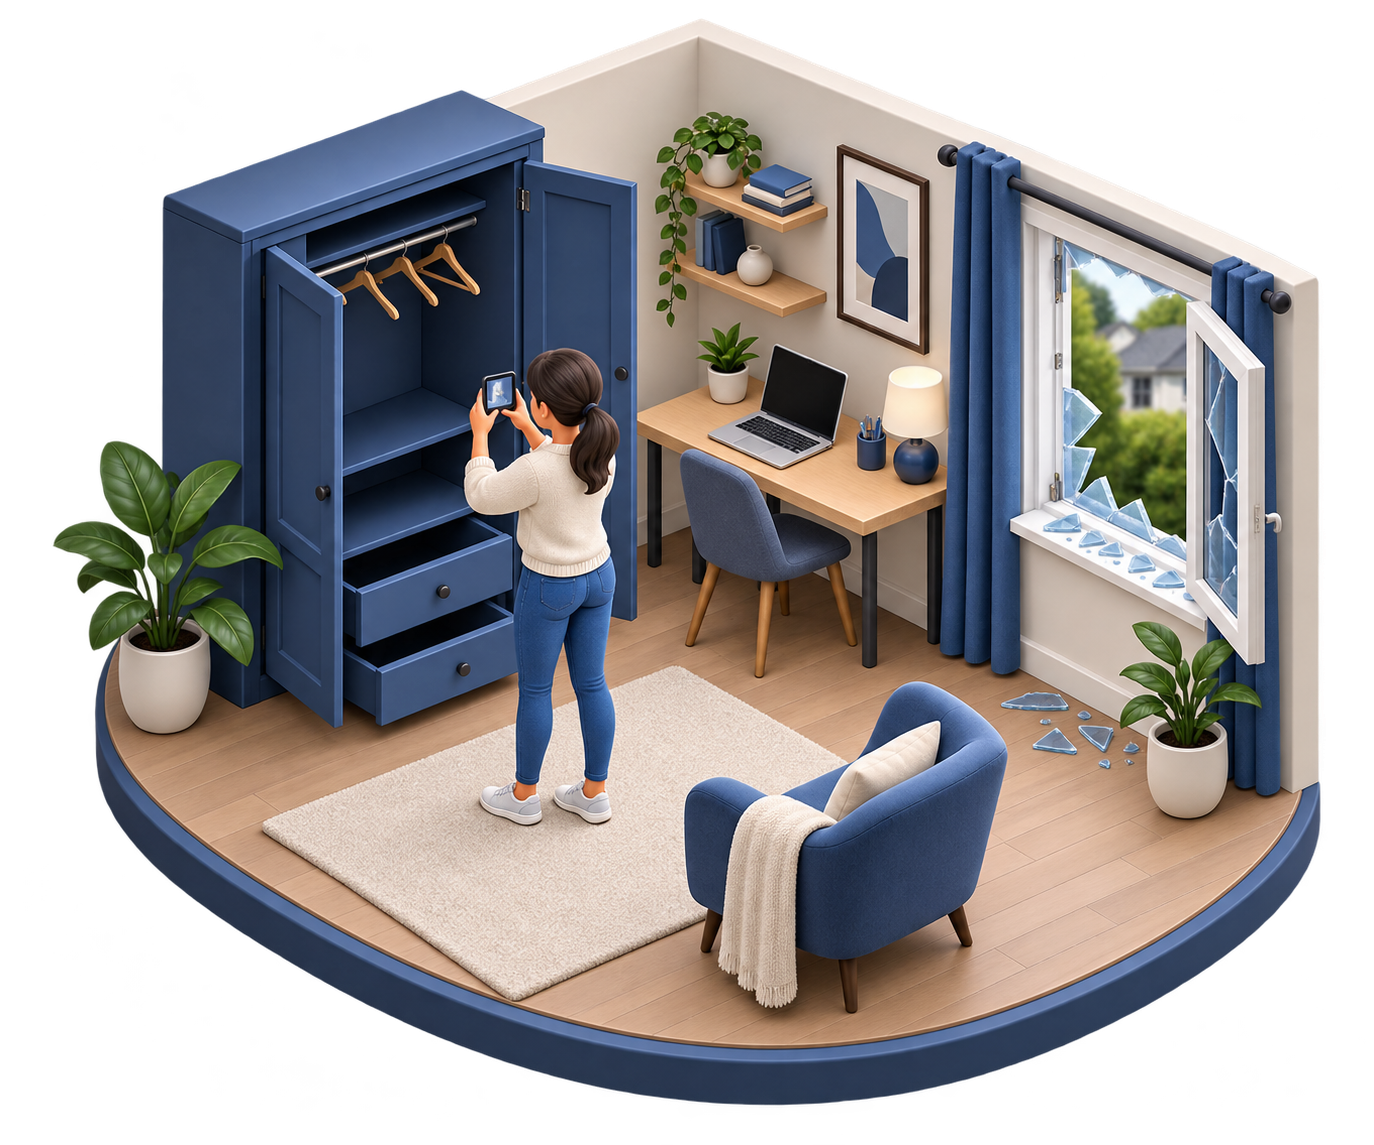
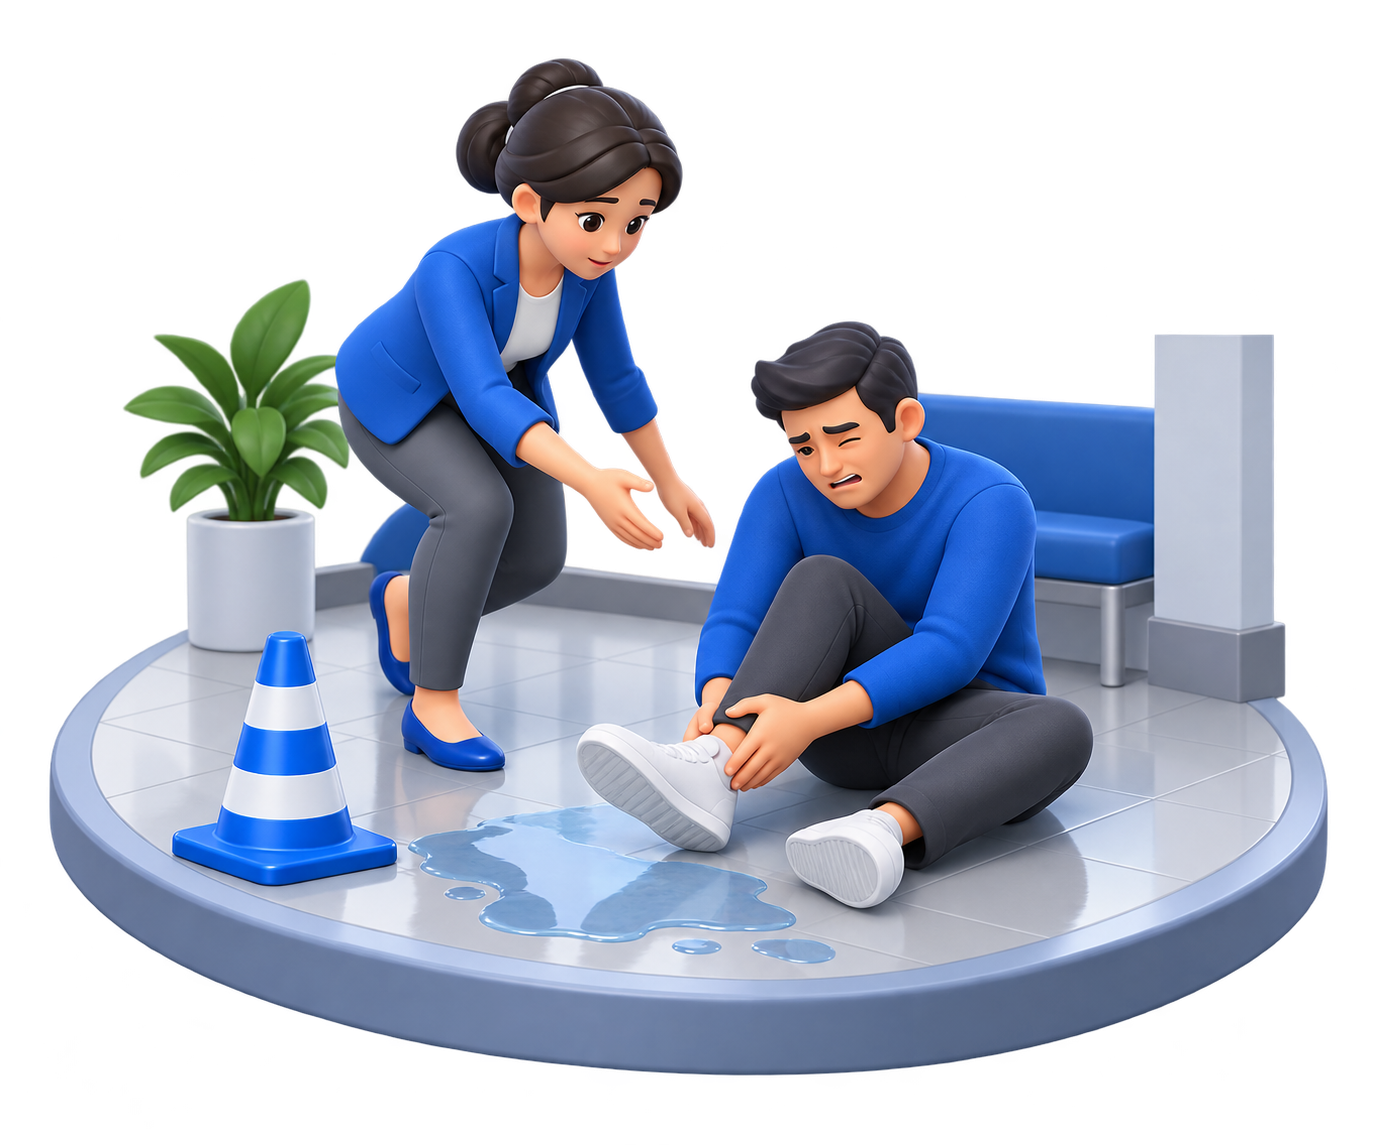
Illustration: stolen belongings

Stolen belongings

Scenario: Personal belongings are taken during a break-in.

What happens next: Keep police details and proof of ownership. Item limits, valuation and any scheduled coverage are part of the assessment.

Illustration: a visitor is injured

A visitor is injured

Scenario: A visitor alleges an unsafe condition caused an injury.

What happens next: Send the allegation to your insurer promptly. Liability and the policy response require investigation rather than an assumed payout.

Actual outcomes depend on the facts and applicable wording. Read claims guidance · Ask about the next step