Warehouse Insurance in Ontario: What It Covers, What It Costs, and How to Get the Right Policy
If you store goods — your own or someone else's — one fire, flood, or collapsed racking system can wipe out a year of profit overnight. Warehouse insurance is the coverage that keeps that single bad day from ending your business.
This guide breaks down exactly what warehouse insurance covers, who needs it, what drives the cost in Ontario, and the gaps that quietly leave warehouse owners exposed. Whether you run a small distribution operation, a 3PL fulfillment centre, or a cold-storage facility, here's what you need to know before you buy.
What Is Warehouse Insurance?
Warehouse insurance is a package of commercial coverages built to protect storage and distribution operations from the specific risks they face — property damage, theft, liability claims, and damage to the goods stored on-site. It is not a single policy. It's a bundle that typically combines commercial property insurance, commercial general liability, and warehouse legal liability into one program tailored to your operation.
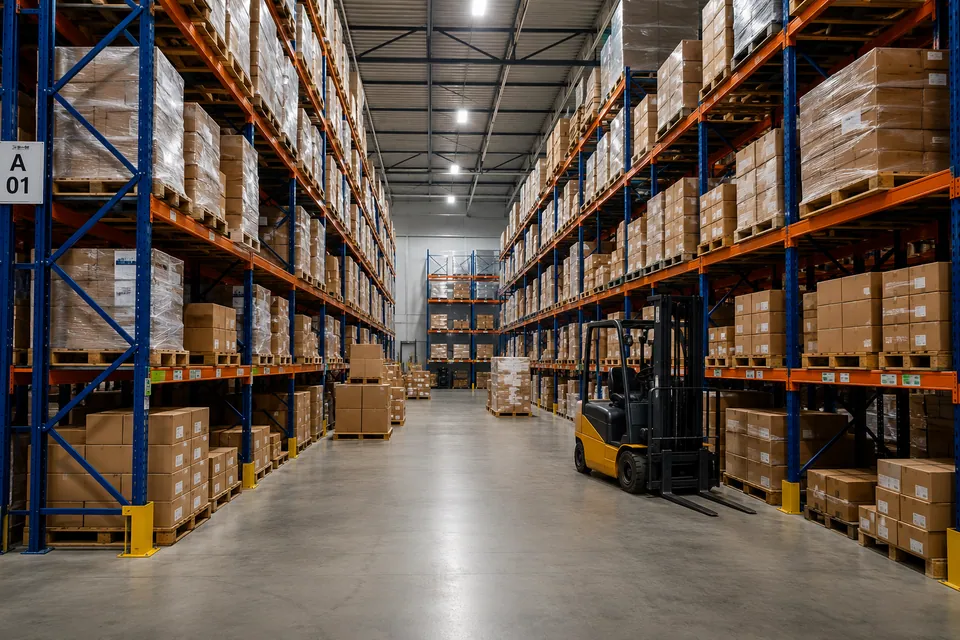
The reason it exists as its own category is simple: a warehouse carries risks a standard business policy was never designed to handle. High-value inventory under one roof, heavy equipment like forklifts, racking systems stacked three storeys high, and — critically — responsibility for goods that belong to other people.
Who Needs Warehouse Insurance?
You need warehouse insurance if your business involves storing, handling, or distributing goods at scale. That includes:
- Distribution centres moving product to retailers or customers
- Third-party logistics (3PL) providers storing and shipping goods on behalf of clients
- Fulfillment centres handling e-commerce orders
- Self-storage and public storage facilities
- Cold-storage and refrigerated warehouses
- Manufacturers with large on-site inventory or finished-goods storage
- Wholesalers and importers holding stock between purchase and sale
If your landlord, lender, or clients require proof of coverage — and most do — a properly structured warehouse policy is also what satisfies those contractual demands.
What Does Warehouse Insurance Cover?
A complete warehouse insurance program in Ontario usually includes the following coverages. The right mix depends on whether you own or lease the building and whether you store your own goods, other people's, or both.
Commercial Property Insurance
Covers the building (if you own it), your equipment, fixtures, racking, and your own inventory against fire, theft, vandalism, water damage, and other covered perils. This is the backbone of any warehouse policy.
Warehouse Legal Liability (Bailee Coverage)
This is the coverage most warehouse owners underestimate. Warehouse legal liability — sometimes called warehouseman's legal liability or bailee coverage — protects you when goods belonging to your customers are damaged, lost, or stolen while in your care, custody, and control. If you store other people's product, your general liability policy will not cover it. This coverage will.
Commercial General Liability (CGL)
Covers third-party bodily injury and property damage — for example, a delivery driver or client who slips on your loading dock, or damage you cause to a neighbouring property. Essential for any operation with people coming and going.
Business Interruption Insurance
Replaces lost income and covers ongoing expenses if a covered loss forces you to halt operations. If a fire shuts your warehouse for three months, this coverage keeps payroll and rent paid while you rebuild.
Equipment Breakdown
Covers sudden mechanical or electrical failure of critical systems — refrigeration units, conveyor systems, HVAC, and electrical panels. For cold storage, this coverage is non-negotiable; a failed compressor can spoil an entire inventory in hours.
Stock and Inventory Coverage
Protects the value of goods you own and store. Pay close attention to how your inventory is valued (actual cash value vs. replacement cost) and whether seasonal spikes in stock are accounted for.
Commercial Auto / Fleet
If you operate delivery vehicles or trucks, your fleet needs its own coverage. Forklifts and on-site equipment may fall under property or a separate floater.
Cyber Liability
Increasingly relevant. Modern warehouses run on inventory management systems, client data, and connected devices. A breach or ransomware attack can stop fulfillment cold — and expose you to client claims.
The Biggest Risks Warehouses Face
Understanding your exposure helps you buy the right limits instead of guessing. The most common — and most expensive — warehouse claims come from:
- Fire — high fuel loads (cardboard, pallets, packaging) make warehouses especially vulnerable
- Water damage — burst pipes, sprinkler discharge, and flooding can destroy stock on the floor
- Theft and break-ins — concentrated, high-value inventory is a target
- Racking collapse — overloaded or damaged racking causes injury and product loss
- Damage to customers' goods — the exposure that triggers warehouse legal liability claims
- Equipment failure — especially temperature-control systems in cold storage
- Slips, trips, and forklift accidents — the leading source of liability claims
How Much Does Warehouse Insurance Cost in Ontario?
There's no flat rate — and any quote you get without details is a guess. Warehouse insurance cost in Ontario depends on the specifics of your operation. The main factors carriers weigh are:
- Size and value of the building and the cost to rebuild it
- Value of inventory and equipment stored on-site
- Whether you store goods belonging to others (this drives liability limits)
- Construction type and age of the building, plus sprinkler and alarm systems
- Type of goods stored — flammable, hazardous, or temperature-sensitive product raises rates
- Location and local fire-protection ratings
- Claims history and loss-control measures in place
- Coverage limits and deductibles you select
A small, modern, sprinklered warehouse storing low-hazard goods will pay far less than an older facility storing high-value or hazardous product. The most reliable way to know your number is to compare quotes from multiple carriers — not to anchor on a single online estimate.
How to Lower Your Warehouse Insurance Premiums
You have more control over your premium than most owners realize. Insurers reward lower risk:
- Install and maintain sprinklers, alarms, and monitored security — the single biggest lever on property rates
- Document your loss-control measures — racking inspections, forklift training, housekeeping standards
- Choose a higher deductible if your cash flow can absorb it
- Bundle coverages into one package rather than buying piecemeal
- Keep your claims history clean — and report risk improvements at renewal
- Review your limits annually so you're not over-insured on a depreciated building or under-insured on growing inventory
Common Warehouse Insurance Mistakes to Avoid
These are the gaps that turn a "covered" loss into an out-of-pocket disaster:
- Skipping warehouse legal liability when you store clients' goods — your CGL won't cover it
- Under-valuing inventory so a major loss is only partially paid
- Ignoring business interruption and having no income while you rebuild
- Letting limits go stale as the business grows
- Assuming flood or sewer backup is included when it often requires an endorsement
How to Get Warehouse Insurance Quotes
The smartest way to buy warehouse insurance is to compare options from multiple insurers based on your operation — building value, inventory, liability exposure, and the type of goods you store. That's exactly what InsuranceGenie does: we match you with the right coverage and competitive quotes so you're not overpaying or under-protected.
Get your warehouse insurance quote today — it takes minutes, and it could save you thousands when it matters most.
Frequently Asked Questions About Warehouse Insurance
What does warehouse insurance cover? Warehouse insurance covers your building, equipment, racking, and inventory against perils like fire, theft, and water damage, plus liability for injuries on your premises and damage to customers' goods stored in your care. Most policies combine commercial property, general liability, warehouse legal liability, and business interruption coverage.
How much does warehouse insurance cost in Ontario? There is no fixed rate. Cost depends on the size and value of your building, the value of stored inventory, whether you hold goods belonging to others, the type of goods, your building's construction and safety systems, and your claims history. Comparing quotes from multiple carriers is the only reliable way to find your actual cost.
Do I need warehouse legal liability insurance? Yes, if you store goods that belong to your customers. Your commercial general liability policy does not cover damage to property in your care, custody, and control. Warehouse legal liability (bailee coverage) is the specific protection for that exposure.
Is warehouse insurance required by law in Ontario? Warehouse insurance is not legally mandated, but it is almost always required by landlords, lenders, and clients through lease agreements and contracts. Operating without it also leaves your business fully exposed to property and liability losses.
What's the difference between warehouse insurance and commercial property insurance? Commercial property insurance covers your physical building and contents. Warehouse insurance is a broader package that adds the liability and bailee coverages specific to storage and distribution — including protection for customers' goods, equipment breakdown, and business interruption.
Does warehouse insurance cover goods in transit? Standard warehouse policies cover goods while stored on your premises. Goods being transported typically require separate cargo or transit coverage. If your operation ships product, ask about adding it.